Tag Archives: Astoria Investments

Astoria Investments Ltd – H1:25 Results Note – Lots of Dry Powder on Hand

Share Code: ARA – Market Cap: R490m – Discount to NAV: c.28%

H1:25 Results: Beyond Diamonds

  • Group NAV slipped -3.5% to $59.85 per share (FY 24: $61.99) or down -9% to 1065cps (FY 24: 1171cps) as the continued diamond bear market took the diamond investments from a c.113cps contribution to Group NAV (end of FY 24) to zero.
  • If the c.113cps diamond investments are reversed from FY 24’s NAV, the Group’s NAV would have grown slightly (+3% p/p).
  • Beyond diamonds, positive developments include a clean exit from ISA Carstens, strong performances from Leatt Corp and Goldrush, and OIH’s exit from A-Tec. Following the period, OIH repurchased some of Astoria’s shares for R105m in cash.

Commentary: Capital Allocation Options

  • Given all the realisations during (and post) the H1:25 period, the Group is currently quite cash flush, and where management allocates this capital will be pivotal in future NAV.
  • Perhaps illustrative of management’s capital allocation intentions is that one of these realisations lowered the Group’s significant exposure to OIH (i.e. dropping portfolio concentration) and another was CFD’s in Astoria’s own share.

Valuation, 12m TP & Implied Return: More than Priced In

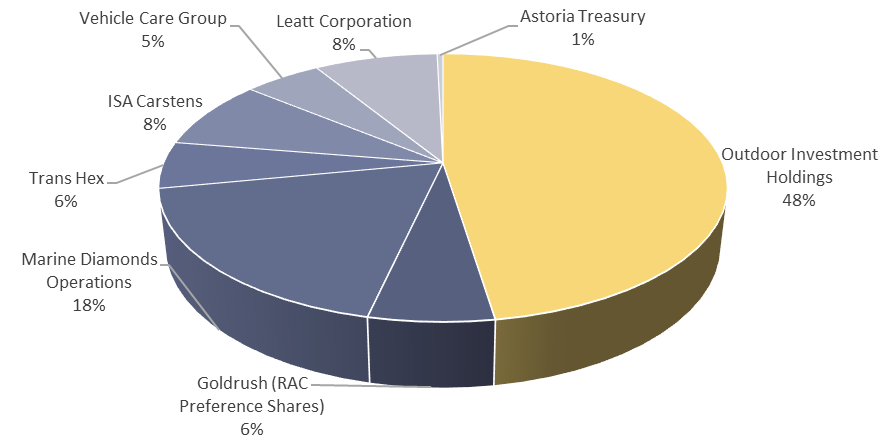
  • We estimate that Astoria’s share is trading at c.28% discount to NAV (Previously: 36%), which includes the partial realisation of OIH, the cash receipt from ISA Carstens and Leatt Corp and Goldrush’s latest share prices (and exchange rates). Cash (& cash equivalent) now forms c.24% of the Group’s NAV.
  • With c.24% of Astoria’s NAV is net cash, the market is basically paying book value for the Group’s investments and offering investors this net cash for “free”.
  • If we take out our calculated “HoldCo discount” of c.16.3% (15.9%), we arrive at a fair value for Astoria’s shares of c.913cps (Previously: 858cps) or c.16% higher than the share price.

Rolling this fair value forward at our Cost of Equity, we arrive at a 12m TP of c.1076cps (Previously: 1020cps) that implies a potential return of c.36% from the current share price.

Astoria Investments Ltd – Results Note – Rough in the Diamond

Share Code: ARA – Market Cap: R418m – Discount to NAV: c.35% (c.32% assuming Diamond investments worth zero)

Q1:25 Results: Diamond Valuations Written Down

  • While Q1 and Q3 results from Astoria are often more administrative (unlisted valuations are usually only updated at Q2 and Q4 period ends), this quarter saw continued pressure on diamond prices and management have prudently written the Marine Diamond valuation to nil and impaired the Trans Hex (i.e. Land Diamond) valuation by 55% to $1.2m.
  • This resulted in the Group’s NAV dropping by -6% in USD & -9% in ZAR (the Rand also strengthened over this quarter or, more accurately, the US Dollar weakened) when compared to the prior quarter (31 December 2024).

Commentary: Gone but Not Nil

  • Despite a zero value, the Marine business continues to operate and can be considered a “nil value option” in Astoria’s NAV.
  • Consensus in the diamond market appears to expect a modest recovery in rough diamond prices (mid-single digits) around late 2025. This recovery is dependent on supply chain efficiencies, marketing effectiveness, and economic stability.
  • Likewise, consensus appears bearish on a full return to pre-pandemic due to the prevalence of lab-grown diamonds.

Idex Diamond Index – 5-year Spot Chart

Valuation, 12m TP & Implied Return: More than Priced In

  • Astoria’s share is trading at c.35% discount to NAV (Previously: 30%) once we update its NAV with current spot/listed prices. This discount is closer to c.32% if we assume that the remaining 4% of NAV in Trans Hex is worth zero.
  • If we take out our calculated “HoldCo discount” of c.15.9% (unchanged), we arrive at a fair value for Astoria’s shares of c.858cps (Previously: 966cps) or c.27% higher than the current share price – but, this fair value is including the diamond valuations as is (i.e. Marine at nil & Land halved) and note our comment about “nil value options” above. Any recovery in the diamond market would translate into upside here.
  • Rolling this fair value forward at our Cost of Equity, we arrive at a 12m TP of c.1020cps (Previously: 1150cps) that implies a potential return of c.51% from the current share price.

Astoria Investments Ltd – Results Note – Marine Diamond Operations Take a Hit

Share Code: ARA – Market Cap: R496m – Discount to NAV: c.30%

FY 24 Results: Disappointing Diamond Market

  • Astoria’s NAV per share decreased to 61.99 USD cents (R11.71) as at 31 December 2024, compared to 79.47 USD cents (R14.54) at the end of the previous financial year, representing a decrease of 22% in USD and 19.5% in ZAR.
  • The primary drivers for the decrease in NAV were the decline in the value of Trans Hex Marine operations and the market prices of the listed assets, Goldrush and Leatt. OIH performed well during the period.
  • OIH’s is exiting A-Tec (sold at approximately the original capital value) and Astoria has accepted a signed sales agreement for its 49% shareholding in ISA Carstens for R66.8m and the outstanding loan from Astoria Treasury for R4.2m.

Commentary: Upcoming Capital Allocation Decisions

  • It is worth noting that both A-Tec (held in OIH) and ISA Carstens exits are at-or-above what Astoria’s NAV was valuing these investments at, which lends comforting evidence as to the tangibility of the Group’s NAV.
  • Furthermore, both exits free up cash that can be deployed. We expect OIH to use most of this cash to grow while Astoria may well apply the cash freed up from ISA Carsten’s exit towards share buybacks given the discount to NAV in the share price making this action quite accretive.

Valuation, 12m TP & Implied Return: Widening of Discount

  • We estimate Astoria’s current NAV as $0.62 or 1149cps a share, implying that the current 800cps share price is at a 30% discount to its NAV.
  • If we take out our calculated “HoldCo discount” of c.15.9% (Previously: 13.6%) from this NAV, we arrive at a fair value for Astoria’s shares of c.966cps (Previously: 1216cps) or c.21.% higher than the current share price.

Rolling this fair value forward at our Cost of Equity, we arrive at a 12m TP of c.1150cps (Previously: 1433cps) that implies a potential return of c.44% from the current share price.

Astoria Investments – Results Note – Navigating the Rough Well

Share Code: ARA – Market Cap: R484m – Discount to NAV: 45%

H1:24/Q2:24 Results: Fully-invested with OIH Paying Dividends

  • With a stronger Rand and lower RACP (soon-to-be renamed ‘Goldrush Holdings’) and Leatt Corp share prices, Astoria’s USD-NAV and Rand-NAV softened -2.9% and -3.5% respectively.
  • During the six months, Astoria invested more into Leatt Corp (LINK), and received a legacy agterskot payout. We currently consider the Group fully invested, but dividend flows from Outdoor Investment Holdings (OIH) should provide incremental capital for deployment & compounding.
  • Finally—as per policy—management have refreshed the Group’s unlisted company valuations, which we specifically discuss in the context of their performance and their peers.

Commentary: Leatt, Goldrush & Diamond Headwinds Cannot Last

  • OIH saw broad growth (excluding Family Pet Centre), Trans Hex (Land & Marine) somewhat bucked diamond trends with good pricing, ISA Carstens showed its quality, and the Vehicle Care Group (VCG) steadily (and responsibly) began scaling.
  • Unfortunately, Leatt Corp (trading its way through excessively stocked wholesale markets) and Goldrush (loadshedding hurting EBITDA margins) saw their share prices under pressure during the period, which created some headwinds to NAV.
  • Loadshedding (appears) gone for the moment and the wholesale market for Leatt should righten itself over time, thus implying upsides in both businesses from these levels.

Valuation, 12m TP & Implied Return: Widening of Discount

  • Astoria’s share is trading at c.45% discount to the current NAV (Previously: 40%) once we update its NAV with current prices.
  • If we take out our calculated “HoldCo discount” of c.14.4% (Previously: 14.2%) from this NAV, we arrive at a fair value for Astoria’s shares of c.1204cps (Previously: 1162cps) or c.54% higher than the current share price.
  • Rolling this fair value forward at our Cost of Equity, we arrive at a 12m TP of c.1417cps (Previously: 1386cps) which implies a potential return of c.82% from the current share price.

Astoria Investments – Results Note – Leatt Investment Concluded

Share Code: ARA – Market Cap: R508m – Discount to NAV: 40%

Q1:24 Results: Currency headwinds

  • Astoria Investments reported its Q1:24 results that show Net Asset Value (NAV) per share decreased -7.7% and -4.8% in USD and ZAR respectively as currency headwinds impacted translations and Goldrush (code: RACP) and Leatt’s (code: LEAT) share price pressure endured for this period.
  • As a reminder, Astoria’s reporting policy for Q1 and Q3 periods is not to perform detailed valuations of unlisted investments (except when developments require an immediate and material change in value). Price changes for listed investments and currencies are reflected on an ongoing basis.
  • In our updated Sum-of-the-Parts (SOTP) valuation below and on the next page, we have done the same and updated our view for the latest share prices and exchange rates.

Commentary: Further Leatt Investments Concluded

  • Astoria’s further acquisition of Leatt Corp’s shares was concluded during this period. We discuss this investment and the underlying business in some detail in our previous results note (LINK) and consider it an attractively priced asset with the deal using Astoria’s equity in a non-dilutive manner.
  • Late in April, Astoria’s management hosted an investor event that was recorded and can be viewed here: LINK.

Valuation, 12m TP & Implied Return: Above Average Discount

  • Updating Astoria’s NAV to current prices, the share is trading at c.40% discount to the current NAV (Previously: 42%).
  • If we take out our calculated “HoldCo discount” of c.14.2% (Previously: 13.9%) from this NAV, we arrive at a fair value for Astoria’s shares of c,1162cps (Previously: 1192cps) or c.42% higher than the current share price.
  • Rolling this fair value forward at our Cost of Equity, we arrive at a 12m TP of c.1386cps (Previously: 1420cps) that implies a potential return of c.69% from the current share price.

Astoria Investments – Results Note – Discount Appears too Wide

Share Code: ARA – Market Cap: R498m – Discount to NAV: 42%

FY 23 Results: A Mixed Bag of Results

  • Astoria’s USD Net Asset Value (NAV) felt pressure and slipped marginally to $0.7947 per share (FY 22: $0.8266 per share), though the Rand NAV was slightly up at 1454cps (FY 22: 1406cps) as the Rand weakened over the period.
  • A decline in diamond prices was a headwind on diamond interests, loadshedding hurt Goldrush’s LPM performance & Leatt’s share price followed its sales down over an extra-ordinary trading period.
  • On the other hand, Outdoor Investment Holdings (OIH) traded (really) strongly (see relative sales performance below), ISA Carstens saw +10% enrolment growth & Vehicle Care Group (VCG) is proving its model nicely.

Commentary: Conservative NAV & Upside Optionality

  • Other than valuing A-Tec in OIH separately as a Norwegian asset and lifting ISA Carsten’s Academy multiple from 6.0x to 7.0x (but it remains well below other listed educational stock multiples), Astoria’s unlisted valuations remain largely consistent with history and, arguably, conservative.
  • A FY 24E normalisation in diamond prices & in Leatt Corp’s trading environment could point to upside in Astoria’s NAV (Leatt & diamond interests are a third of the Group’s NAV).

Valuation, 12m TP & Implied Return: Above Average Discount

  • Updating Astoria’s NAV to current prices, the share is trading at an above-sector-average c.42% discount to current NAV (Previously: 34%) despite its strong growth in NAV (+32.4% y/y CAGR in Rand-NAV since management took over on 1 December 2020)
  • If we take out our calculated “HoldCo discount” of c.13.9% (Previously: 15.0%) from this NAV, we arrive at a fair value for Astoria’s shares of c,1192cps (Previously: 1152cps) or c.49% higher than the current share price.
  • Rolling this fair value forward at our Cost of Equity, we arrive at a 12m TP of c.1420cps (Previously: 1365cps) which implies a potential return of c.77% from the current share price.